Binomial Tree Model: Option Price and Binomial Option Pricing Explained
Understanding the Binomial Tree Model
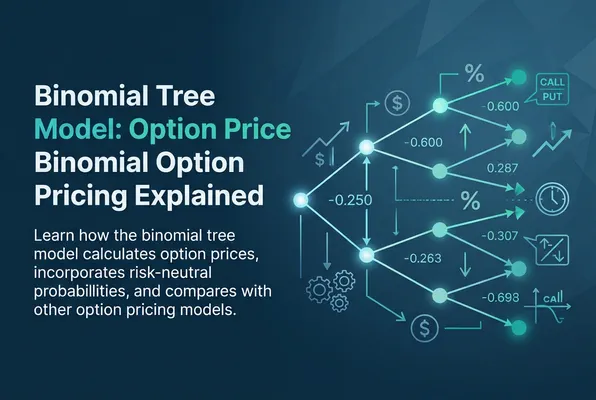
The Binomial Tree Model is one of the most widely used methods for valuing options and other derivative instruments. Unlike formulas that rely on continuous mathematics, this model breaks down the life of an option into multiple discrete time intervals, creating a “tree” of possible price paths for the underlying asset. At each node, the price can move up or down by a specific factor, allowing analysts to calculate the option’s value by working backward from expiration to the present.
This approach was first introduced by Cox, Ross, and Rubinstein in 1979, and it remains a cornerstone technique in quantitative finance, equity compensation valuation, and corporate finance departments worldwide. For companies managing employee stock options (ESOs) or complex derivative instruments, understanding the binomial tree model is essential for accurate financial reporting and compliance.
How the Binomial Tree Model Works
Mathematical Foundations of Binomial Option Pricing
The binomial option pricing model provides a discrete framework for calculating the fair value of a derivative by considering alternative future market scenarios. Unlike continuous-time approaches, binomial option pricing divides the option’s lifetime into individual periods, making it possible to evaluate how changes in the underlying asset affect the final valuation. The central objective is to determine the option price that is consistent with the absence of arbitrage opportunities.
At each time step, the price of the underlying asset can increase or decrease according to predefined factors. These movements generate a binomial distribution of possible outcomes when the model is interpreted over multiple independent steps. However, the probabilities used for valuation are risk-neutral probabilities rather than necessarily representing the actual likelihood of market movements. This distinction allows the model to calculate the expected value of the option under a risk-neutral framework and discount it using the risk-free rate.
The resulting pricing model offers a practical connection between probability theory and financial mathematics. By examining the possible future values of an asset and the corresponding contractual payoffs, analysts can establish the present option value without having to forecast the investor’s actual return.
The Basic Structure
At its core, the binomial tree model assumes that, over a short period, the price of an underlying asset can only move in one of two directions: up or down. This creates a branching “tree” structure where each node represents a possible price at a specific point in time.
The model is built using the following key components:
- Underlying asset price (S): The current market price of the stock or asset
- Strike price (K): The agreed-upon price at which the option can be exercised
- Time to expiration (T): The total duration until the option expires, divided into discrete steps
- Up factor (u) and down factor (d): Percentage changes representing upward and downward price movements
- Risk-free interest rate (r): Used to discount future payoffs back to present value
- Volatility (σ): A measure of how much the underlying asset’s price fluctuates
- Number of steps (n): The number of discrete time intervals in the tree
Building the Tree Step by Step
- Divide the time to expiration into n equal intervals.
- Calculate the up and down factors using volatility and the length of each time step, typically derived using the formula u = e^(σ√Δt) and d = 1/u.
- Construct the price tree, starting from the current stock price and branching outward with each node representing a possible future price.
- Determine the option payoff at each terminal node (the final branches of the tree) based on the difference between the stock price and strike price.
- Work backward through the tree, discounting the expected payoffs at each node using risk-neutral probabilities until you arrive at the present value of the option today.
Risk-Neutral Valuation
A critical concept within the binomial tree model is risk-neutral valuation. Rather than trying to predict actual probabilities of price movements, the model assumes investors are indifferent to risk, allowing calculations to use a simplified “risk-neutral probability” (p) for upward and downward movements. This probability is calculated as:
p = (e^(rΔt) - d) / (u - d)
This risk-neutral framework ensures that the model remains arbitrage-free and mathematically consistent, which is why it’s trusted by auditors, valuation professionals, and financial regulators.
Why Use the Binomial Tree Model?
Flexibility for American-Style Options
One of the biggest advantages of the binomial tree model over other valuation approaches, such as the Black-Scholes model, is its ability to handle American-style options, which can be exercised at any time before expiration. Because the tree structure evaluates the option’s value at every node, it can easily incorporate early exercise decisions, something the Black-Scholes formula cannot natively do.
American and European Options: Exercise Decisions
The distinction between American and European options becomes particularly important when determining whether early exercise should be considered. European options can generally be exercised only at expiration, while American options may be exercised at any eligible time before or on the expiration date. A valuation method must therefore account for the contractual exercise conditions of the instrument.
For an American option, the model compares the value of immediate exercise with the value of continuing to hold the contract at every relevant node. The exercise decision is determined by selecting the greater of these alternatives. This process is commonly described as the requirement to exercise at each node when immediate exercise is more valuable than continuation, subject to the contract’s terms.
For European options, the valuation follows the contractual payoff at expiration and the backward calculation of discounted continuation values. This distinction illustrates why the same underlying asset, strike price, and expiration date may produce different valuations depending on the exercise rights attached to the option.
Accommodating Complex Features
The binomial tree model can also accommodate:
- Vesting schedules for employee stock options
- Changing volatility over the life of the option
- Dividend payments at specific points in time
- Variable interest rates across different periods
- Non-standard exercise behavior, such as blackout periods or performance conditions
This flexibility makes it a preferred choice for companies valuing employee equity compensation, where real-world complexities often don’t fit neatly into simpler models.
Intuitive and Transparent
Unlike the more abstract Black-Scholes formula, the binomial tree model offers a visual, step-by-step representation of how an option’s value evolves over time. This transparency makes it easier for finance teams, auditors, and stakeholders to understand and validate the assumptions behind a valuation.
Binomial Tree Model vs. Black-Scholes Model
| Feature | Binomial Tree Model | Black-Scholes Model |
|---|---|---|
| Time structure | Discrete (multiple steps) | Continuous |
| Early exercise | Supported | Not natively supported |
| Complexity | More computationally intensive | Simpler, closed-form solution |
| Flexibility | High (handles vesting, dividends, variable volatility) | Limited |
| Best suited for | American options, employee stock options | European options |
While Black-Scholes remains popular for its simplicity and speed, the binomial tree model is generally considered more accurate for instruments with early exercise features or complex vesting conditions, making it especially relevant for equity compensation valuation.
Applications of the Binomial Tree Model
Employee Stock Option Valuation
Companies issuing stock options to employees often need to determine the fair value of these grants for financial reporting purposes under standards like ASC 718 or IFRS 2. The binomial tree model is frequently preferred in these scenarios because it can incorporate vesting periods, expected employee turnover, and early exercise behavior, factors that are common in real-world equity compensation plans but difficult to model with simpler formulas.
Pricing Exotic and Complex Derivatives
Beyond standard options, the binomial tree model is also used to price more complex derivative instruments, including barrier options, convertible bonds, and other structured financial products where payoff structures depend on the path of the underlying asset’s price.
Risk Management and Scenario Analysis
Financial institutions use binomial trees not just for valuation but also for scenario analysis and risk management, since the tree structure naturally illustrates a range of possible future outcomes and their associated probabilities.
Limitations of the Binomial Tree Model
Despite its strengths, the binomial tree model has some limitations worth considering:
- Computational intensity: As the number of time steps increases for greater accuracy, the calculations become more resource-intensive.
- Sensitivity to assumptions: Inputs like volatility and the number of steps can significantly affect the final valuation, requiring careful calibration.
- Convergence requirements: A relatively high number of steps is often needed for the binomial model’s results to converge closely with continuous-time models like Black-Scholes.
Despite these challenges, modern computing power has largely mitigated concerns about computational intensity, making the binomial tree model practical even for complex, multi-year equity compensation structures.
Convergence, Accuracy, and Computational Efficiency
An important consideration when applying the binomial model is the relationship between the number of time steps and the accuracy of the estimated value. As the tree becomes more refined, the discrete representation can approximate the behavior of a continuous-time asset-price process more closely. Under suitable assumptions and appropriate parameter choices, the binomial model converges toward the value implied by the corresponding continuous-time model.
One common theoretical connection is geometric Brownian motion underlying price dynamics, which assumes that the asset price evolves continuously with a drift component and stochastic volatility. Binomial trees approximate this type of process through successive upward and downward movements. The quality of the approximation depends on the selected parameters, the number of periods, and the consistency of the model assumptions.
Nevertheless, increasing the number of periods also increases computational requirements. A basic recombining tree can be evaluated efficiently, but complex contracts and additional state variables may require substantially more calculations. Consequently, the binomial approach can be computationally slower than the Black–Scholes formula, particularly when a large number of time steps or repeated valuations are necessary. The appropriate level of refinement should therefore balance numerical accuracy with computational efficiency.
A Practical Guide to the Binomial Model
A practical guide to the binomial approach should begin with a clear definition of the instrument and its contractual characteristics. Analysts must identify the current underlying asset price, strike price, expiration date, volatility, applicable risk-free rate, and exercise style. They should also determine whether dividends, changing market conditions, or other contract-specific features need to be included.
The next stage involves selecting the number of time steps and calculating the corresponding upward and downward movements. Once the price tree has been constructed, the terminal payoffs are calculated and the option values are propagated backward through the tree. For American-style contracts, the calculation must incorporate the possibility of early exercise, while European-style contracts follow their specified expiration payoff.
Finally, the calculated result should be evaluated through sensitivity analysis. Changing volatility, the risk-free rate, time to expiration, or the number of time steps helps reveal which assumptions have the greatest influence on the final valuation. Comparing results with an appropriate alternative method can also help identify implementation errors and assess numerical convergence.
A well-documented application should record the assumptions, parameter choices, and computational method used. This makes the valuation easier to reproduce, review, and adapt when market conditions or contractual requirements change.
Best Practices for Applying the Binomial Tree Model
- Use an appropriate number of time steps: More steps generally improve accuracy but increase computation time.
- Calibrate volatility carefully, using historical data, implied volatility, or a blend of both depending on the asset and valuation context.
- Incorporate realistic assumptions about dividends, vesting, and expected exercise behavior, especially for employee stock options.
- Validate results against alternative models like Black-Scholes for sanity checks when applicable.
- Document all assumptions thoroughly to support audit and compliance requirements.
Final Thoughts
The Binomial Tree Model remains an indispensable tool in modern finance, offering a flexible, transparent, and accurate method for valuing options and complex derivative instruments. Its ability to handle early exercise features, vesting schedules, and changing market conditions makes it particularly valuable for companies managing employee stock option programs and other equity compensation plans.
For organizations navigating the complexities of equity compensation valuation, understanding and correctly applying the binomial tree model can mean the difference between compliant, defensible financial reporting and costly valuation errors. Whether you’re a CFO, financial analyst, or HR professional overseeing equity programs, mastering this model is a worthwhile investment in your financial toolkit.
FAQ
What is the Binomial Tree Model used for?
How does the Binomial Tree Model differ from the Black-Scholes Model?
Is the Binomial Tree Model accurate for valuing employee stock options?
What inputs are required to build a Binomial Tree Model?
Written by
Dominik KonoldCEO & Founder
Dominik Konold is the CEO and founder of Finidy GmbH, specializing in share-based compensation and treasury accounting. With a background in audit and investment banking, he is a certified Professional Risk Manager (PRMIA) and lectures for the Association of Public Banks and the Academy of International Accounting.
Related Posts
SAYE Plan: How Save As You Earn Schemes Work
This article explains the UK SAYE scheme, its rules, savings options, and tax benefits.
Dry Income: Meaning, Tax Impact & Management Tips
This article explains what dry income is, why it occurs, how it affects business owners and investors, and which tax strategies can help manage tax liabilities and maintain financial stability.
Accelerated Vesting: How to Accelerate Your Vesting Schedule for Stock Options & Restricted Stock
This guide explains accelerated vesting, including single- and double-trigger acceleration, vesting schedules, equity grants, and what happens to employee equity during major corporate events.
Ready to simplify your equity programs?
See how Incentrium helps you manage share-based compensation with ease. Book a demo to learn more.
Book a Demo